
Chefs’ Warehouse (CHEF) has drawn investor attention after a strong run, with the stock up 87% year to date and 110% over the past year, closing at $116.42 on 1 October 2026.
Recent trading has kept that momentum alive, with a 3.43% 1 day share price return on the latest move and a 21.75% 90 day share price return. Chefs’ Warehouse has delivered a 110% total shareholder return over the past year and a very large total shareholder return over three years, suggesting buyers have steadily been pricing in stronger growth expectations and a different view of the company’s risk profile.
Scan how Chefs’ Warehouse compares with other fast moving consumer and distribution plays by reviewing our hand picked list of 19 high quality undiscovered gems.
Bulls argue Chefs’ Warehouse has earned a premium after its surge, while bears see sentiment running ahead of fundamentals. The recent move forces a direct question: Do the current numbers justify this price?
Most Popular Narrative: 5% Undervalued
Chefs’ Warehouse last closed at $116.42, compared with a widely followed fair value narrative of $122.00. This frames the recent surge as only slightly ahead of that underpinning story rather than detached from it.
Enhanced scale and strategic discipline in portfolio management, including natural attrition of non-core, low-margin business and the intent to reallocate freed capacity to specialty and high-value customers, positions the company to benefit from industry consolidation while supporting both gross profit and operating leverage.
See why 6 investors see Chefs’ Warehouse as 5% undervalued.
Result: Fair Value of $122.00 (UNDERVALUED)
Still, the fair value story for Chefs’ Warehouse can break if rising labor and supply chain costs squeeze its already thin net margin or if acquisitions disrupt rather than integrate.
Find out about the key risks to this Chefs’ Warehouse narrative.
Another View: Chefs’ Warehouse On Rich Earnings Multiples
On the flip side of that fair value story, Chefs’ Warehouse trades on a P/E of 51.6x, compared with 18x for the wider US Consumer Retailing group and 28.9x for peers, while the fair ratio sits at 26.4x. That premium leaves far less room if expectations reset even slightly.
See what the numbers say about this price — find out in our valuation breakdown.
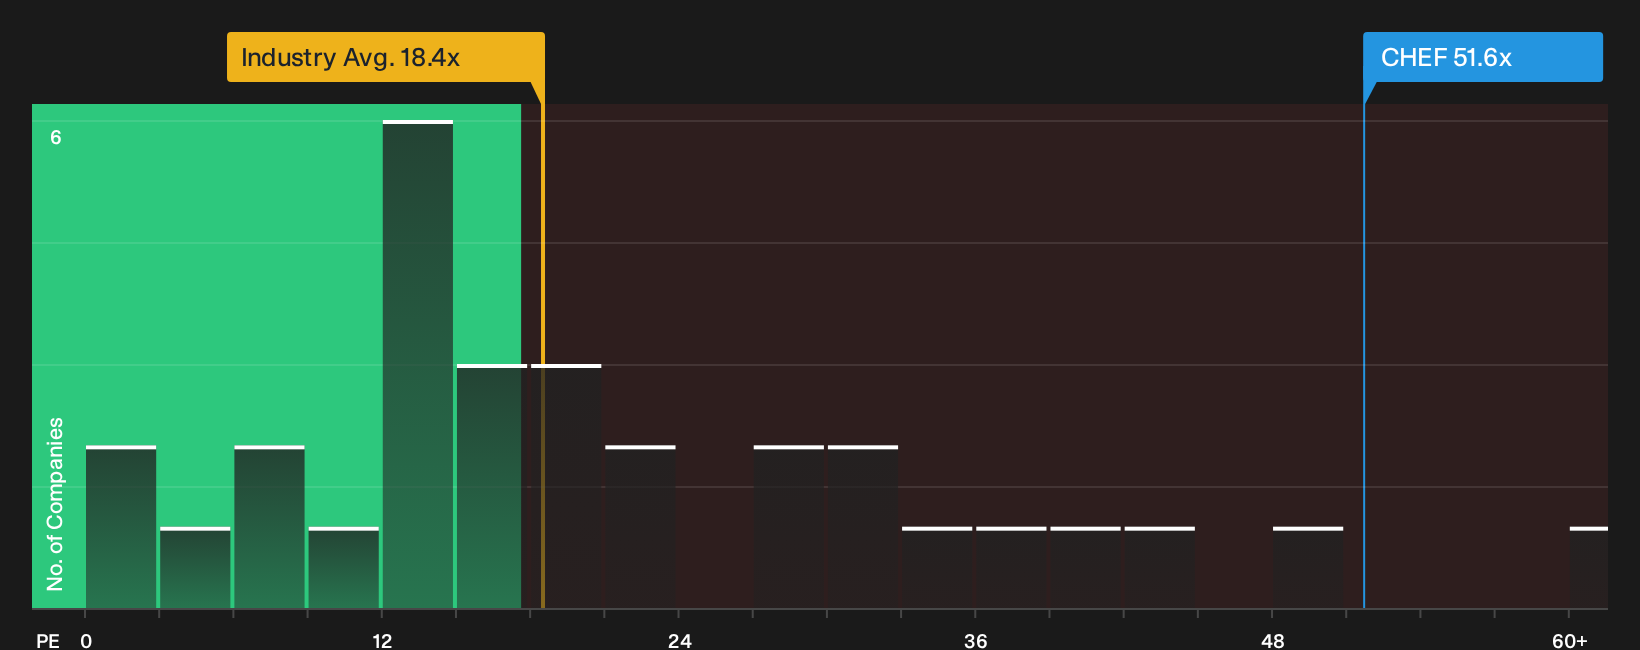 NasdaqGS:CHEF P/E Ratio as at Oct 2026Next Steps
Mixed views on whether Chefs’ Warehouse’s recent surge is justified or stretched. Act while the data is fresh and weigh both sides using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Chefs’ Warehouse?
Do not stop with Chefs’ Warehouse. Use fresh screener ideas to pressure test your thesis, widen your watchlist and avoid missing opportunities that match your investing style.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com


